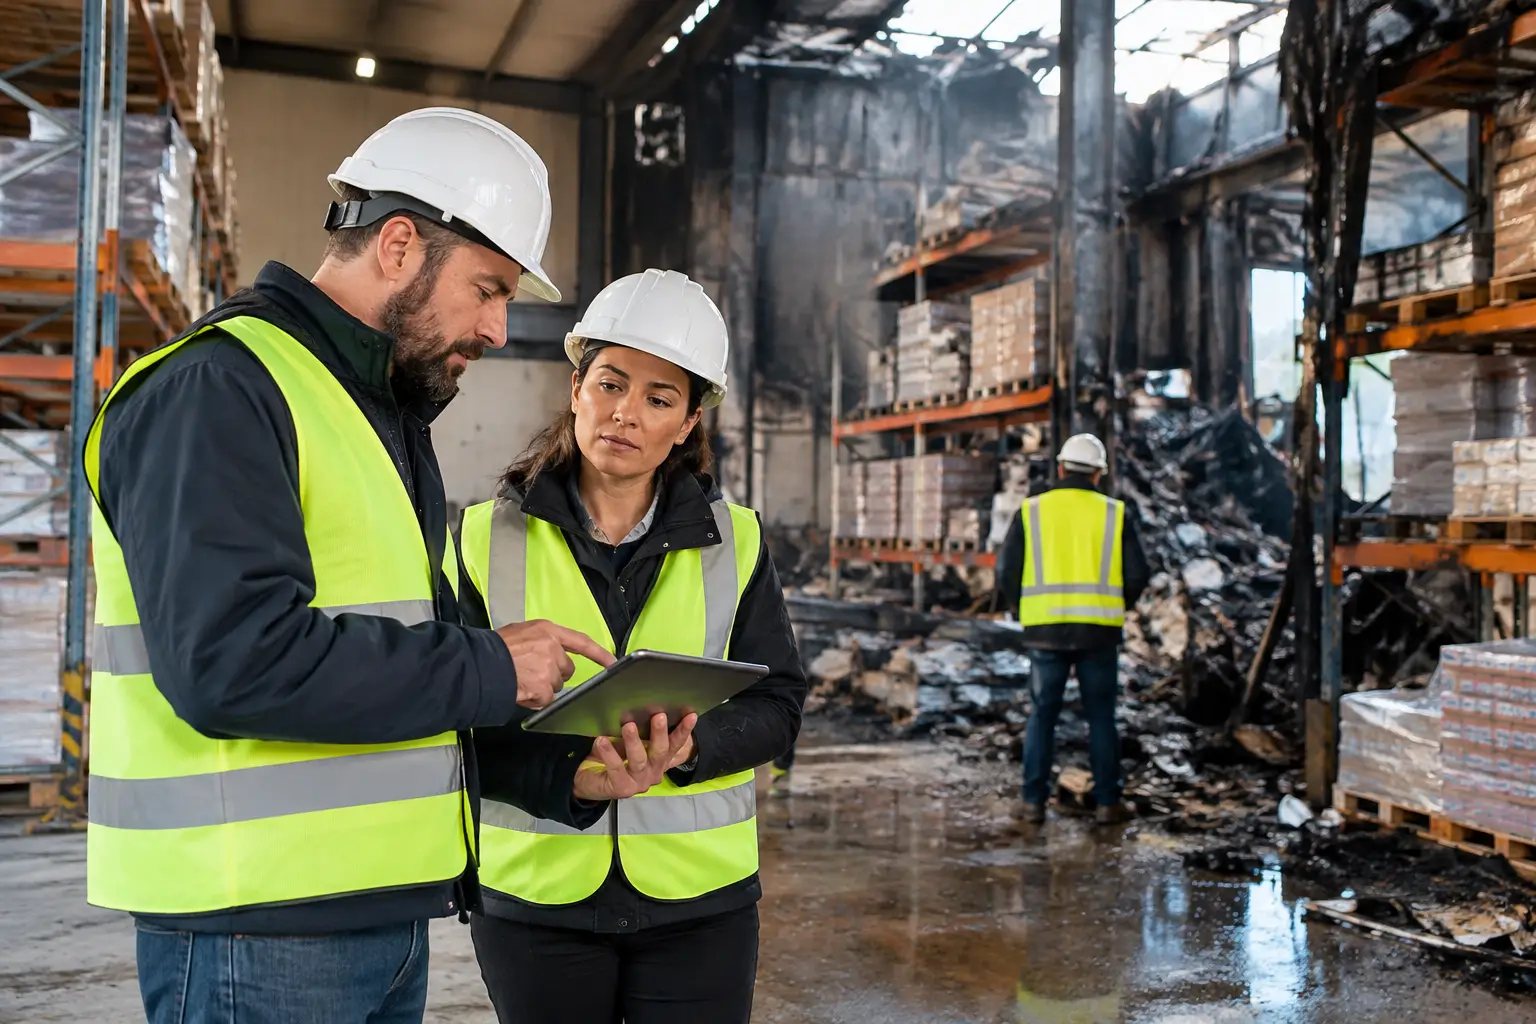
A warehouse fire claim begins long before the adjuster arrives. The first hours after a fire can determine whether a business preserves critical evidence, protects undamaged inventory, and maintains a credible path to recovery. For Texas operators managing distribution centers, manufacturing space, storage facilities, or mixed-use warehouses, the claim is not simply a property matter. It is an operational continuity event.
The objective is to stabilize the site, document the loss, meet policy conditions, and make well-supported decisions before cleanup or reconstruction changes the evidence. A disciplined response also helps leadership understand what coverage may apply beyond the building itself, including inventory, equipment, lost income, extra expense, and contingent obligations to customers.
Stabilize the Site Before Rebuilding Begins
Life safety and emergency-response requirements come first. Once local authorities permit access, the business should secure the premises against further damage, theft, weather exposure, and unauthorized entry. This duty is common in commercial property policies: the insured is expected to take reasonable steps to protect covered property after a loss.
That does not mean beginning broad demolition or discarding damaged materials. Fire, smoke, sprinkler discharge, and suppression efforts can create overlapping damage categories. Removing inventory, machinery, racking, electrical components, or building materials too early may make it harder to establish the cause, scope, or value of the loss.
Assign one internal point of contact for the claim. This person should coordinate with the carrier, broker, public officials, restoration vendors, and company leadership while maintaining a record of key communications and decisions. In a larger organization, this role may sit with operations, finance, facilities, or risk management. What matters is clarity. Multiple employees giving inconsistent directions can create avoidable delays.
Build the Record for a Warehouse Fire Claim
A strong claim file is built from contemporaneous evidence, not recollection weeks later. Photograph and video the exterior, interior, inventory areas, loading docks, office space, equipment, utilities, and any temporary protective measures. Capture wide views to establish context, then close views of labels, serial numbers, damaged materials, and affected structural elements.
Document conditions before restoration work begins, including smoke migration into areas that may appear intact. Smoke and soot can affect electronics, stored goods, packaging, HVAC systems, and finished inventory even where flames did not reach. Water damage from sprinklers or firefighting activity can also create later corrosion, mold, or product-quality concerns.
Financial records matter just as much as site photographs. Gather recent inventory reports, purchase orders, invoices, fixed-asset schedules, payroll data, production records, sales reports, lease documents, and prior appraisals. A warehouse that carries seasonal inventory or customer-owned goods may require additional records to establish who owned what property and which contractual obligations apply.
Keep a daily claim log. Record the date, time, attendee, purpose, and outcome of each call or site meeting. Save emails, estimates, vendor proposals, and receipts for emergency mitigation. This creates a usable history when questions arise about what was authorized, why an expense was necessary, or when a business-interruption period began.
Identify the Coverage Questions Early
Commercial property coverage is essential, but the right recovery analysis rarely stops there. Policy language, endorsements, sublimits, deductibles, valuation provisions, and exclusions govern the outcome. The operational impact of a fire often extends across several coverage sections.
Building coverage may apply if the company owns the structure. Tenants should review lease obligations and tenant-improvement coverage, particularly where they have made substantial improvements to office areas, refrigeration systems, specialized wiring, or loading infrastructure. Business personal property may include inventory, machinery, tools, computers, furniture, and materials used in operations.
Business income coverage can be equally significant. It is designed to address qualifying lost income during a covered period of restoration, subject to the policy's terms. Extra expense coverage may help with reasonable costs to continue operations, such as temporary warehouse space, overtime, expedited shipping, equipment rental, or relocation of staff and inventory. The distinction matters: an expense that reduces downtime may be commercially sensible, but it still should be evaluated against the policy language before assumptions are made.
For warehouse operators, several issues deserve early review:
- Whether inventory is valued at actual cash value, replacement cost, selling price, or another stated basis.
- Whether customer goods, property in the insured's care, custody, or control, or goods held on consignment are covered under the applicable policy terms.
- Whether spoilage, temperature change, contamination, or damaged packaging creates a separate coverage or valuation issue.
- Whether the policy includes ordinance or law coverage for code-driven rebuilding costs, such as sprinkler upgrades or accessibility requirements.
- Whether service interruption, utility failure, supplier disruption, or civil-authority restrictions may affect the operation.
The answer depends on the policy and the facts of the event. A tailored commercial property program should be reviewed as an integrated structure rather than as a single building limit.
Control Cleanup Costs Without Delaying Recovery
Emergency mitigation is often necessary, but cost control should begin immediately. Obtain written scopes of work from restoration vendors and separate emergency stabilization from full reconstruction whenever practical. Ask vendors to identify what they found, what they recommend, and how each activity relates to fire, smoke, water, or potential contamination.
Do not select a vendor solely because they can arrive first. Capacity, documentation standards, equipment, pricing, and experience with industrial or warehouse environments all matter. The wrong cleanup approach can damage recoverable inventory, disrupt forensic review, or produce invoices that are difficult to reconcile later.
At the same time, waiting for every coverage question to be resolved before mitigating can be a mistake. The business has a duty to prevent additional loss, and delayed drying, boarding, or security can worsen the damage. The practical approach is controlled action: preserve evidence, notify the carrier promptly, document the need for emergency work, and track each expense.
Quantify the Operational Loss, Not Just the Physical Damage
The physical repair estimate is only one part of a warehouse fire claim. Leadership should map the operational consequences: orders that cannot be fulfilled, production that cannot continue, inventory that must be relocated, customers that require expedited shipment, and employees whose work is disrupted.
Create a recovery plan that identifies the critical path to resuming operations. It may be possible to restore shipping from a temporary location before the primary facility is rebuilt. A manufacturer may prioritize electrical service and a key production line over office finishes. A distributor may need to focus first on usable dock access, racking safety, and inventory verification.
Finance teams should track actual performance against a reasonable pre-loss baseline. Preserve monthly and weekly sales data, order backlog, margins, payroll, and unusual costs. If sales decline after the fire, the question is not always whether revenue fell. The claim analysis may examine why it fell, whether the decline resulted from the covered loss, and what income would likely have been earned without the interruption.
This is also the point to communicate carefully with customers and suppliers. Commercial relationships can be protected by setting realistic delivery expectations, arranging alternate fulfillment, and documenting any additional logistics costs. A rushed promise that cannot be met can turn a property loss into a customer-retention problem.
Work With the Adjuster From a Position of Organization
The adjuster needs information to evaluate the loss, and timely cooperation helps move the file forward. Provide organized records, identify the appropriate internal subject-matter contacts, and ask for clarity on requested documents, inspections, and next steps. If the carrier requests a sworn proof of loss, pay close attention to the deadline and the supporting detail required.
Professional cooperation does not require accepting an incomplete scope, unclear valuation, or unsupported reserve position. Review estimates and inventory calculations closely. Ask questions when assumptions do not reflect the facility's actual operations, specialized equipment, or replacement requirements. If the loss involves complex business-income calculations, large inventory values, or disputed causation, outside accounting, engineering, or legal support may be appropriate.
A brokerage partner can help coordinate the insurance side of the process, but the business should retain ownership of operational decisions. BIN supports clients with tailored commercial property coverage and structured claim coordination designed around the realities of their facilities, vehicles, assets, and continuity requirements.
Reduce Friction Before the Next Loss
The best time to examine a fire claim is before one occurs. Confirm building and business-personal-property values, update inventory practices, retain offsite copies of financial records, and review lease responsibilities. Test whether business-income limits and extended-period provisions reflect the time it would actually take to rebuild, replace equipment, restock, and restore customer volume.
A warehouse fire can expose gaps that were invisible during ordinary operations. A well-organized response gives the business a better chance to recover its property, protect customer commitments, and make the next decision from evidence rather than urgency.